
The Waiting Game Changes the Playbook
When the Federal Reserve signals that rate cuts are coming but keeps pushing back the timeline, fixed-income investors face a specific kind of problem: they want safety, they want yield, and they do not want to be locked into duration that could erode value if rates stay elevated longer than expected. Floating-rate Treasuries – formally known as Floating Rate Notes, or FRNs – sit in a part of the market that rarely makes headlines, but they are drawing quiet, consistent interest from exactly this cohort of short-duration seekers.
The appeal is mechanical rather than speculative. FRNs reset their interest payments weekly, tied to the 13-week Treasury bill rate. That means investors are not betting on a rate path – they are simply collecting whatever the short end of the curve is paying, updated in near real time. In an environment where the Fed has held rates at multi-decade highs far longer than most forecasters expected, that automatic adjustment becomes genuinely attractive.
What Floating Rate Notes Actually Are
The Treasury Department first introduced FRNs in 2014, a relatively recent addition to the government securities toolkit. They are issued with two-year maturities, but because the coupon floats with the 91-day T-bill rate plus a spread set at auction, they behave more like a rolling cash instrument than a traditional bond. The spread is locked in at issuance, so investors know the premium they will earn above the benchmark rate for the full two-year term.
This structure makes FRNs distinct from short-term T-bills in one important way: investors do not have to constantly roll positions. A buyer who purchases a newly issued FRN gets two years of automatic rate adjustment without the administrative burden of reinvesting every four, eight, or thirteen weeks. For institutional allocators managing large cash positions, that efficiency matters more than it might seem from the outside.
Why the Rate Cut Delay Matters So Much
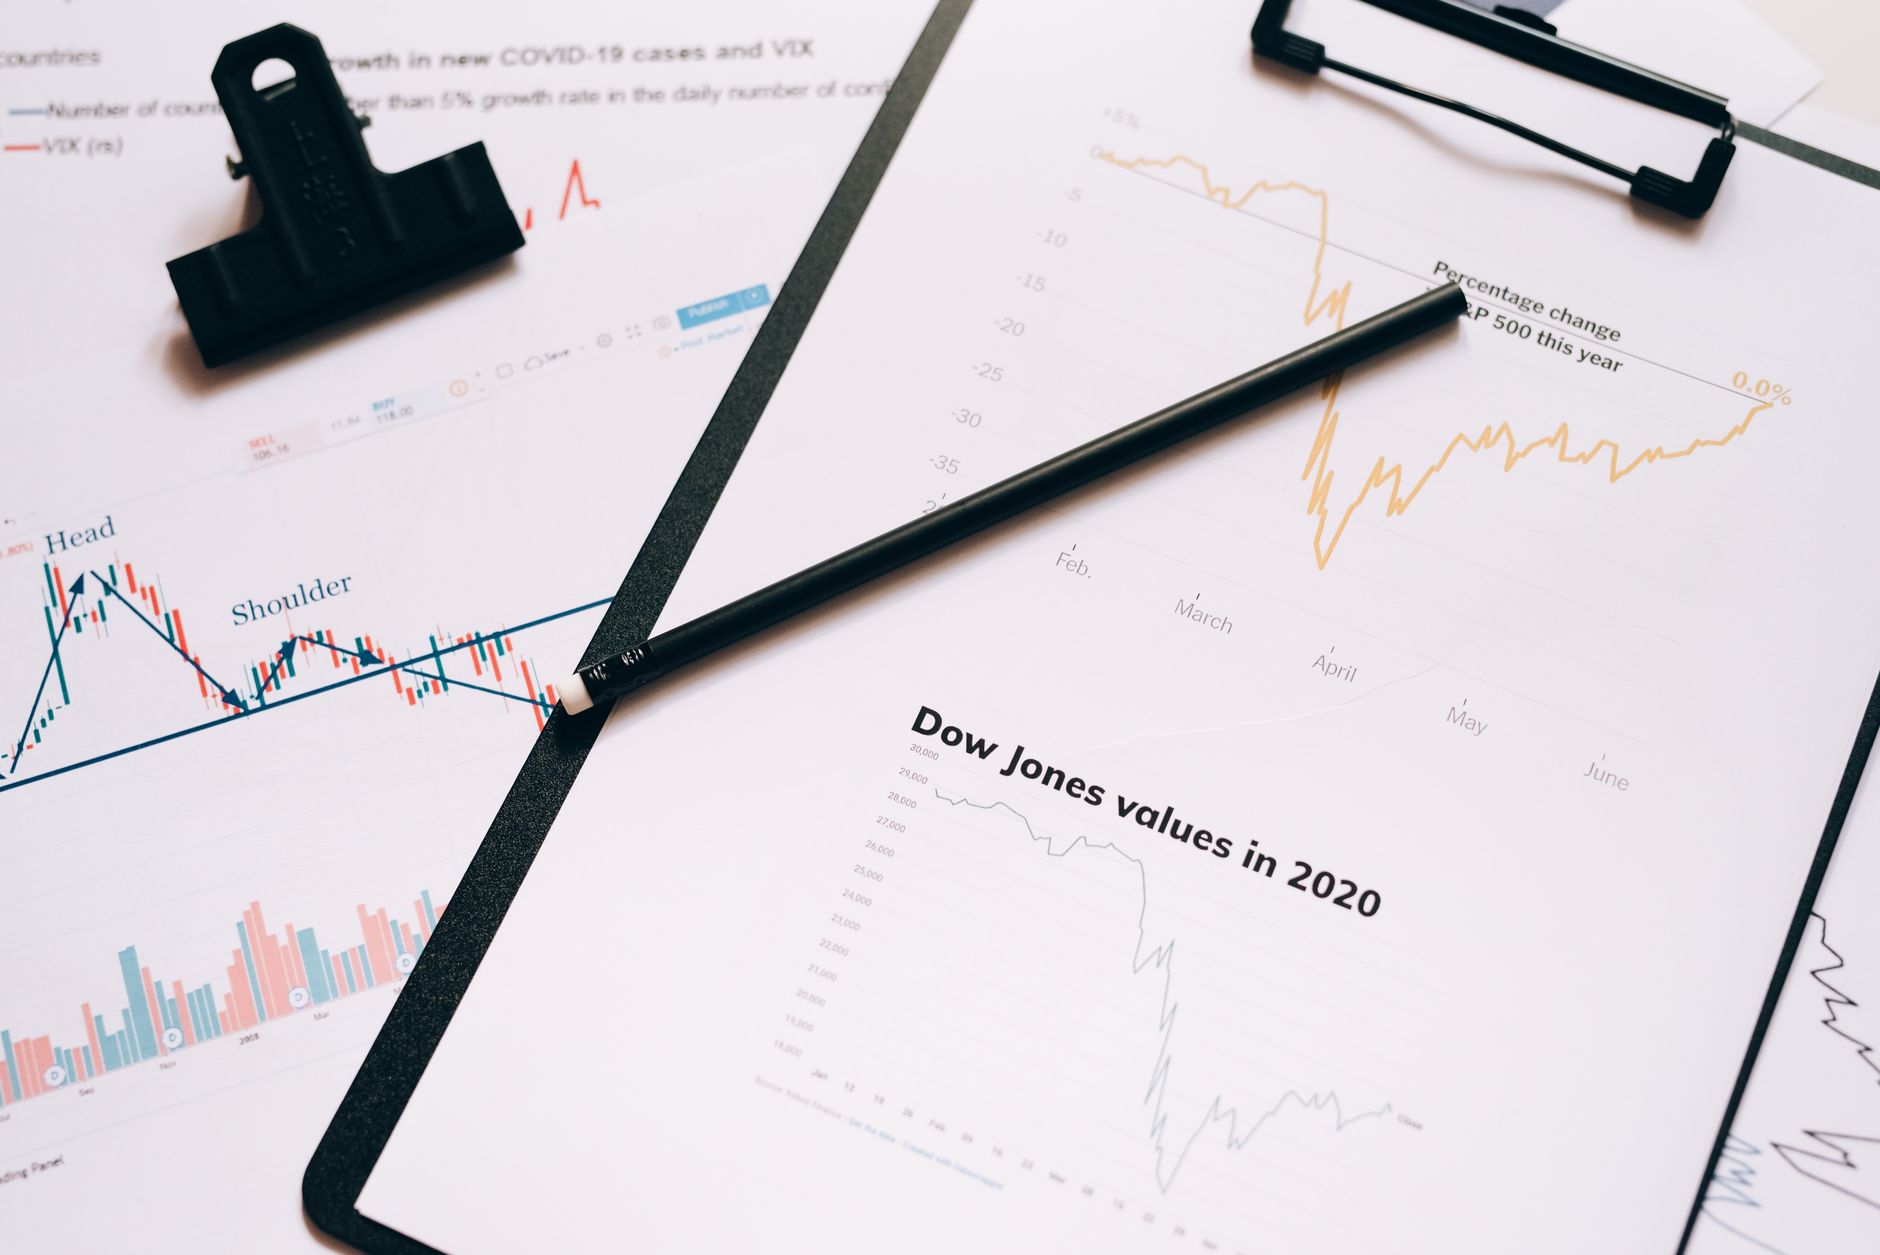
Markets entered 2024 expecting several Fed rate cuts before year-end. That consensus kept shifting as inflation proved stickier than anticipated, and each revision pushed the expected first cut further out. Investors who had positioned in fixed-rate short-term bonds found themselves holding instruments that looked reasonable at purchase but were losing relative competitiveness as the short end of the curve continued paying elevated yields.
FRN holders faced none of that anxiety. The weekly reset meant their income automatically kept pace with prevailing rates. There was no need to sell and reinvest at a higher rate, no duration mismatch to manage, and no price erosion from the duration extension that affects fixed-rate bonds when rates move against the holder.
The contrast with traditional two-year Treasury notes is worth spelling out. A fixed two-year note purchased when yields were at a certain level will keep paying that fixed coupon regardless of what happens next. If rates go higher and stay higher, that note becomes less attractive relative to new issuance. An FRN adjusts continuously, which means its market price stays close to par and its income tracks whatever the market is actually paying. That stability of principal, combined with adaptive income, is a combination that looks different from most alternatives without taking on credit risk.
Investors who have been watching asset-backed securities regain shelf space among cautious allocators will notice a parallel logic at work here: when uncertainty makes duration a liability, the market gravitates toward instruments that either reset frequently or mature quickly. FRNs offer the former with full government backing.
Who Is Actually Buying
The buyers tend to cluster in predictable categories. Corporate treasurers managing operating cash face a constant tension between yield and liquidity. Money market funds provide liquidity but often yield slightly less than a comparable FRN position. Locking into longer-term fixed rate instruments introduces price risk that corporate boards and CFOs prefer to avoid. FRNs sit in a useful middle ground.
Conservative individual investors, particularly those approaching or in retirement, have also developed more interest in the FRN structure. The direct Treasury market, accessible through TreasuryDirect.gov, allows individual buyers to purchase FRNs at auction with no fees. The government guarantee removes credit risk entirely, and the floating structure removes the duration concern that makes longer bonds uncomfortable when rate direction is unclear.
The Spread Dynamic and What It Signals
The spread set at FRN auction is determined by competitive bidding, which means it reflects market demand in real time. When the spread comes in thin – close to zero or even slightly negative in some past auctions – it signals strong demand for the floating structure itself. Buyers are willing to accept a lower premium above the T-bill rate in exchange for the reset mechanism and the safety of the government guarantee.
Recent auction dynamics have shown demand holding up even when the spread on offer is modest. That behavior suggests the FRN market is not simply attracting buyers who could not find better yield elsewhere – it is attracting buyers who specifically value the structural properties of the instrument. The reset mechanism is the product, not just a feature.
What makes this moment particularly interesting is that if and when the Fed does begin cutting rates, FRN income will decline automatically. Buyers entering now are essentially accepting that tradeoff: they get today’s elevated short-term rate, and they accept that future cuts will reduce their income accordingly. For investors who believe cuts are still some time away, or who would rather have certainty of principal over certainty of income, that tradeoff reads as rational. The harder question is whether the delay in cuts will be long enough to justify choosing the floating structure over a fixed short-term note that locks in today’s yield for the full term – and that calculation shifts every time the Fed speaks.