
The catastrophe bond market is having a moment that reinsurers have been quietly engineering for years. Record issuance volumes, widening spreads, and a fresh wave of institutional capital flowing into the space signal that cat bonds are no longer a niche corner of alternative risk transfer – they are becoming a primary tool for offloading peak catastrophe exposure.
Why Reinsurers Are Pushing Risk Into Capital Markets Now
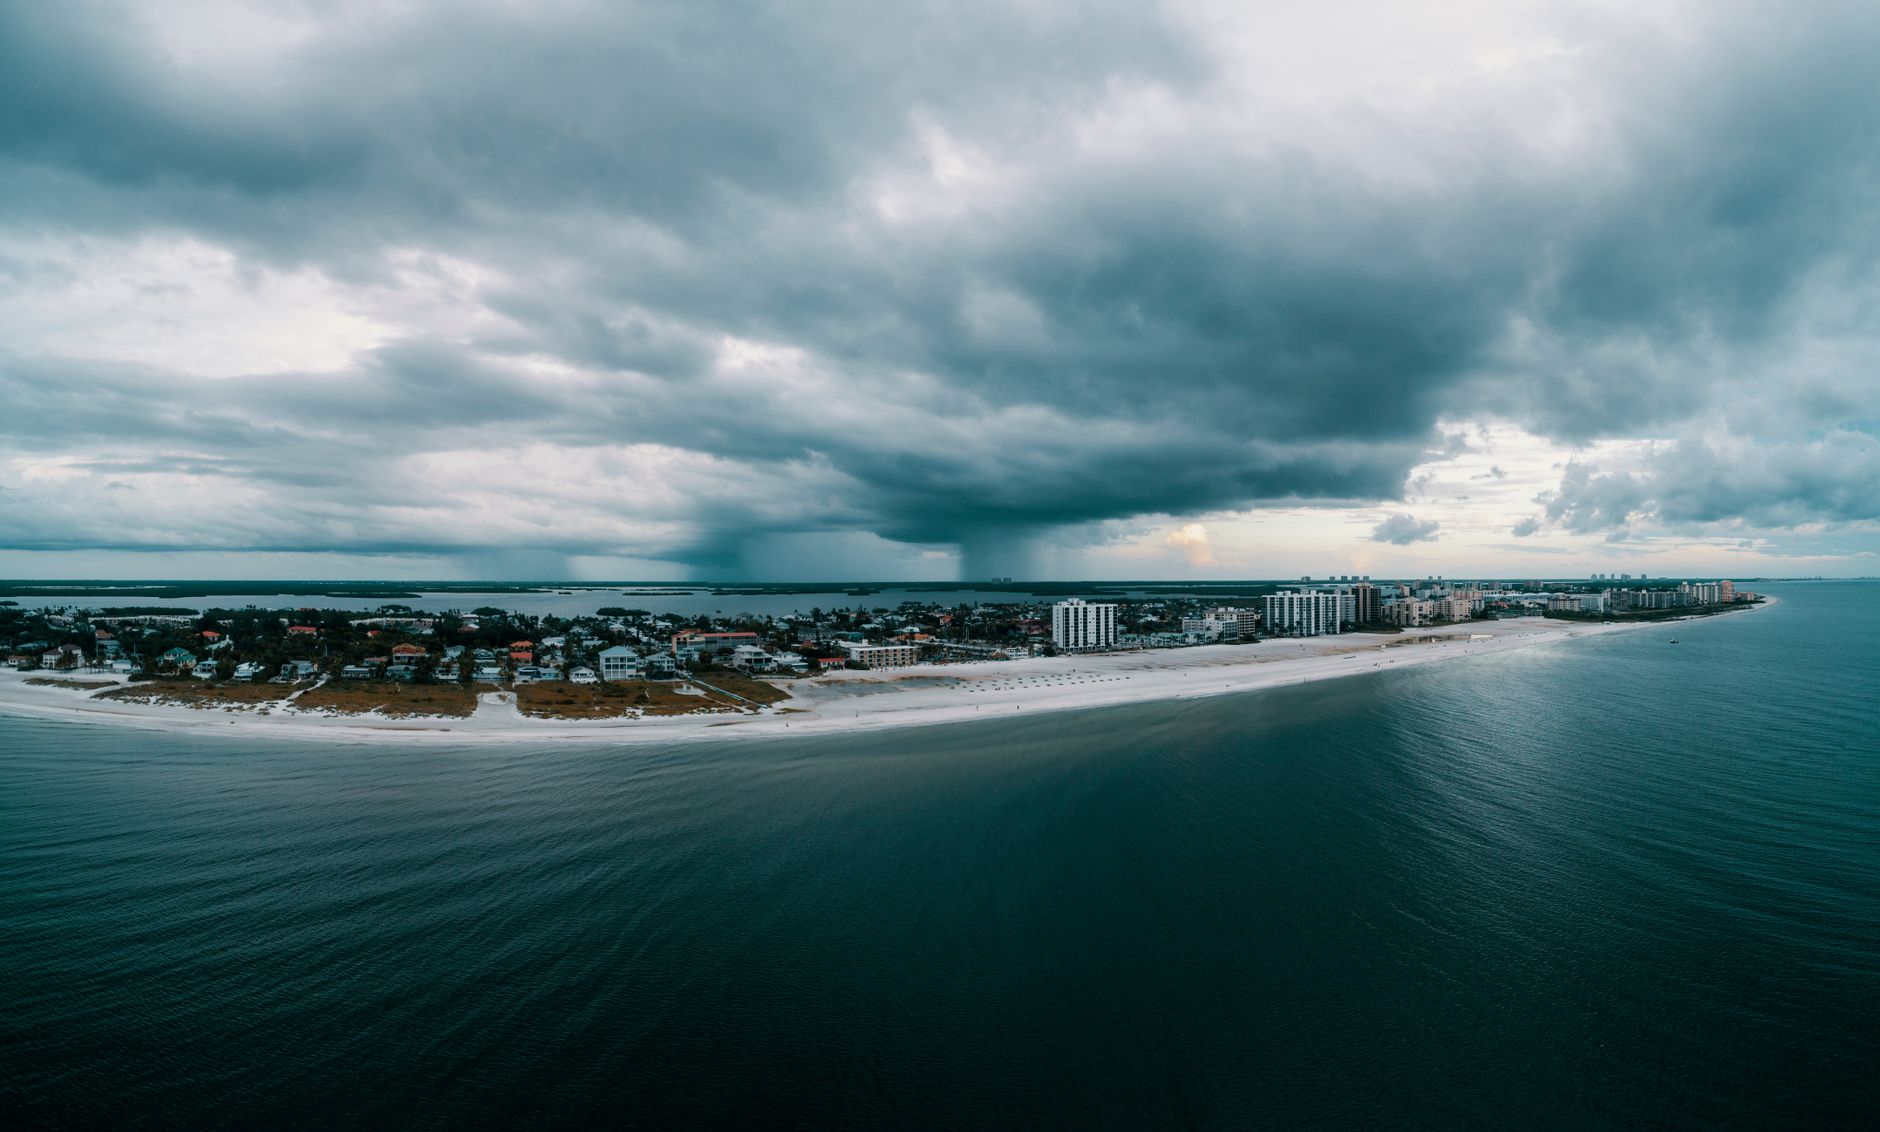
Catastrophe bonds work by transferring specific disaster-related financial risk from an insurer or reinsurer to capital market investors. The issuer sets up a special purpose vehicle, which sells bonds to investors. If a defined catastrophe event – say, a Florida hurricane exceeding a certain insured loss threshold – occurs during the bond’s term, investors lose some or all of their principal. In exchange for bearing that risk, they collect above-market coupon payments throughout the bond’s life. The structure is clean, the risk is isolated, and the trigger conditions are defined in advance.
Reinsurers are pushing more risk into this structure for a straightforward reason: traditional retrocession capacity – the reinsurance of reinsurers – has become expensive and scarce. After a series of costly natural disaster years, retrocessionaires tightened terms and raised prices sharply. Capital markets, by contrast, offer a different risk appetite. Pension funds, hedge funds, and dedicated insurance-linked securities funds are willing to take on catastrophe exposure precisely because it carries no correlation to equity markets or interest rate cycles. For a pension fund manager looking to diversify a fixed income sleeve, that uncorrelated return stream is genuinely useful.
The timing of the current issuance surge is not accidental. Reinsurers tend to push cat bond deals to market ahead of peak hurricane season – locking in coverage before the statistical risk window opens. A deal structured and priced in late spring provides protection through the Atlantic season without leaving the reinsurer exposed during negotiations. The market has essentially built a seasonal rhythm around this need, and investors have come to expect a pipeline of new paper each spring.
Spreads have also moved in investors’ favor following several loss years. When catastrophe bonds pay out – as some did following major hurricane and wildfire events – surviving bonds reprice at higher spreads to attract replacement capital. That repricing has made the current vintage of cat bonds more attractively priced than issues from five or six years ago, drawing in allocators who previously found the risk-return tradeoff marginal. Higher base rates on the floating-rate coupon structure have further boosted all-in yields, making the asset class genuinely competitive with high-yield corporate bonds on a yield basis, with the added benefit of low default correlation.
Who Is Buying and What They Are Getting
The buyer base for catastrophe bonds has broadened considerably. Dedicated insurance-linked securities funds remain the core, but they are increasingly joined by multi-strategy hedge funds treating cat bonds as a tactical allocation, and by pension funds and endowments building out standalone ILS sleeves. The asset class now has enough secondary market liquidity – though still limited compared to investment grade credit – that larger institutions can manage position sizing without being entirely locked in to maturity.
What investors are actually purchasing is a probability-weighted bet against a specific peril in a specific region. A bond might cover U.S. Gulf Coast named storm losses above a certain industry loss index threshold, with a modeled annual expected loss of around two percent. The investor earns a spread above that expected loss – the excess is compensation for uncertainty in the models, tail risk beyond the modeled scenario, and the illiquidity of the instrument. When the models are right and no event occurs, the investor keeps the spread and returns principal at maturity. When the models are wrong or an event exceeds thresholds, the loss can be partial or total.
Model risk is the central tension in cat bond investing, and it is not fully resolved by the sophistication of the catastrophe modeling firms that underpin most transaction structures. Models are calibrated on historical data, and climate-related shifts in storm intensity, wildfire behavior, and flood patterns introduce uncertainty that historical data alone cannot fully capture. A bond priced on the assumption that a Category 5 hurricane makes Florida landfall roughly once every twenty years may be mispriced if the actual frequency has shifted. Investors carrying this risk need to understand that they are not just bearing known probabilities – they are bearing the uncertainty around those probabilities.
Secondary market trading in cat bonds has matured to the point where prices reflect real-time information during an active storm season. When a major hurricane threatens the Gulf Coast, bonds with Gulf Coast wind exposure trade down sharply, even before any loss is confirmed. This mark-to-market dynamic is useful for transparency but uncomfortable for investors who think of the asset class as a buy-and-hold carry trade. A fund with redemption terms that don’t match the bonds’ liquidity profile can find itself in trouble during a storm season even if no bond ultimately triggers.
The structural variety within the market has also expanded. Beyond standard indemnity and index-triggered bonds, issuers are experimenting with multi-peril structures covering earthquake and wind risk in a single instrument, and with shorter duration bonds that reset pricing more frequently. Some newer structures link to parametric triggers – satellite-measured wind speed or seismic intensity at a specific location – rather than modeled industry losses. Parametric structures pay out faster and eliminate the lengthy loss adjustment process, but they introduce basis risk: the event might trigger the bond while the issuer’s actual losses are lower than the payout, or vice versa.
The Limits of the Model and What Comes Next
The cat bond market’s growth depends on continued investor confidence that the risk is priced correctly and that the modeling framework is sound. That confidence has survived several significant loss events, but it has also never been tested by a truly catastrophic convergence – say, a major earthquake and a major hurricane in the same quarter, or a multi-year cluster of above-average loss years that depletes capital faster than it can be replaced. The market has grown precisely because those scenarios have not materialized in a way that broke the structure, but the structure itself has never faced its worst-case scenario at scale.
Reinsurers offloading peak risk into capital markets through cat bonds are, in a real sense, outsourcing their most dangerous exposures to investors who may be less equipped to assess the tail. The sophistication gap between a dedicated ILS analyst and a pension fund credit committee allocating to a cat bond fund is real. If losses cluster and fund performance turns negative, the question of whether that institutional capital stays in the market – or exits at exactly the wrong moment – remains genuinely open.
Frequently Asked Questions
What is a catastrophe bond and how does it work?
A catastrophe bond transfers disaster-related financial risk from an insurer to investors via a special purpose vehicle. Investors earn above-market coupons but risk losing principal if a defined catastrophic event occurs.
Why are catastrophe bond spreads higher now than in previous years?
Several costly natural disaster years caused losses on existing bonds and pushed new issuance to reprice at higher spreads to attract replacement capital, making the current vintage more attractive to yield-seeking investors.